 Javier Rivera
The ResourceWise U.S. Unbleached Corrugated Box Cost Index: A Cost-Based Alternative for Corrugated Contract Price Adjustments
 ResourceWise: Oct 2, 2026, 9:37:04 AM
 Jennifer Hawkins: Oct 2, 2026, 9:29:05 AM
 ResourceWise: Oct 1, 2026, 1:54:23 PM
 Javier Rivera : Sep 14, 2026, 10:20:43 AM
Asian glycol markets are expected to remain fundamentally tight in the coming weeks. Low import availability, improving but still low operating...
Jennifer Hawkins : Aug 4, 2026, 10:13:15 AM
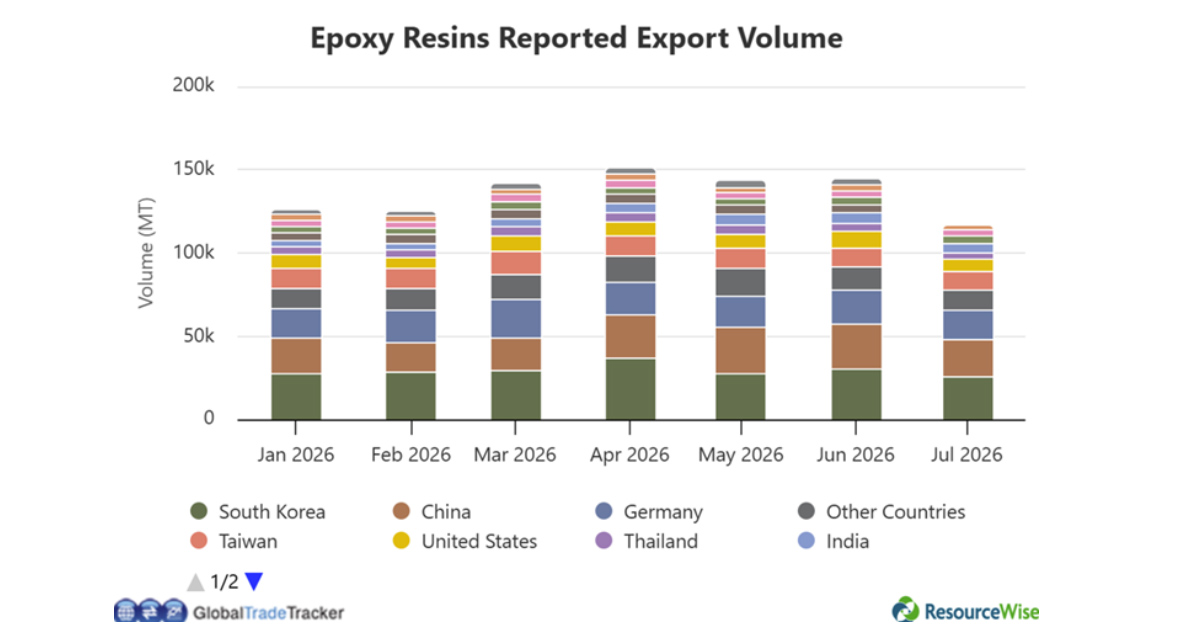
Epoxy resin prices rose sharply in early 2026 as feedstock costs increased, but weak demand and shifting geopolitical risk created an uneven...
ResourceWise : Mar 2, 2026, 3:10:27 PM
Coordinated military strikes by the United States and Israel on Iranian targets in late February have triggered the most significant disruption to...